Sell CVV Telegram Shop 2025: A Comprehensive Guide
Discover how to sell CVV codes through Telegram shops in 2025, with essential tips and precautions.
Choose from any of our gift cards to give to your loved ones
Top Pick for Selling CVV on Telegram Shops
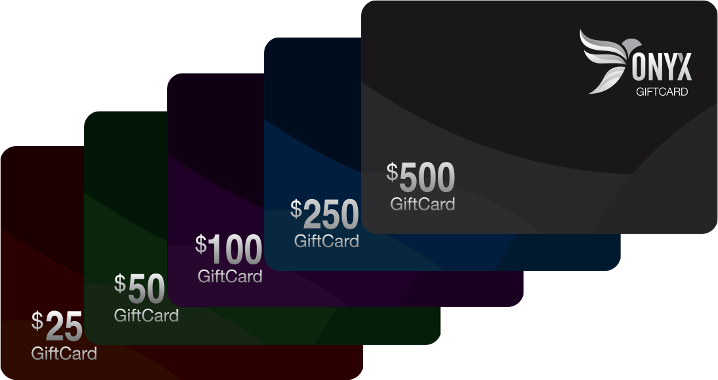
Redeem your gift cards at any of our Merchants
You can purchase a gift card from any of these locations

Onyx Gift Cards is a Grenadian company designed to introduce, market and manage gift cards systems in Grenada for retailers and corporations. We are enthusiastic about the effect and influence we will have on the local market. We intend to expand our systems regionally with a range of product offerings and services.
Gift cards are the preferred way of giving and receiving gifts. They carry a monetary value that can be redeemed for gifts at your favorite store.
Onyx GiftCards are “Open Gift Cards” which means that they can be redeemed at multiple merchant locations. They are standard credit card size, can fit into the average wallet and made of PVC plastic. Onyx GiftCards are Barcoded for security and safety for the consumer and bear a disclaimer at the back.
Onyx Giftcards can be bought with a branded Card backer which is black in colour and is designed to fit the card. There is an area to write a brief message to the recipient as well.
Selling or buying CVV data is card fraud, and Telegram channels that advertise stolen card numbers with fast cash-out are criminal marketplaces. In the United States, using someone else's card details to move money breaks federal law, and the buyer of a stolen CVV carries the same exposure as the seller. This guide explains what those shops trade, why the offers fall apart, and how to keep your own card data out of them.
The CVV is the three or four digit code printed on a payment card, used to prove the person typing the number holds the physical card. A card data shop trades that code together with the full card number, expiry date, and cardholder name, often bundled with billing address details.
Sellers sort their lists by card type, bank country, and account balance range. The buyer pays in crypto, receives the data, and then tries to spend it before the real cardholder notices. No part of that chain is legal.
No. Card numbers belong to the account holder, the issuing bank, and the payment network, not to whoever copies them. Buying, selling, trading, or using them without permission falls under identity theft and access device fraud statutes in the US and similar laws in other countries.
Telegram does not make a shop anonymous. Payment trails, chat logs, wallet addresses, and IP records all leave evidence, and investigators use them. A channel that promises total privacy is selling a story.
Penalties scale with the amounts involved. A single unauthorized charge can lead to felony charges once prosecutors show intent to defraud, and moving the money through other people's accounts adds money laundering counts on top.
Fast cash-out claims serve two purposes. They attract buyers, and they hide the fact that many of these shops run scams on their own customers.
The cardholder spends hours on the phone, the issuer absorbs the loss, and merchants eat chargebacks plus fees. Small businesses feel it most, since a run of disputed orders can shut down a payment processor account.
Banks then reissue cards, which costs money and disrupts automatic payments tied to the old number. Customers with a frozen card miss subscriptions, travel bookings, and bills. Everyone caught in that loop loses time.
Prices rise for the rest of us. Fraud losses get built into interchange fees and retail prices, so the cost lands on ordinary shoppers.
Basic habits stop most card data theft before it starts. None of them require technical skill.
Card skimmers at fuel pumps and ATMs are an old problem that still works. Give the reader a tug before you insert your card, and cover the keypad when you type a PIN.
Call the number on the back of your card and ask for a block and a replacement with a new number. Then change passwords on shopping accounts that stored that card, and turn on two-factor authentication.
Report the theft at IdentityTheft.gov and file a complaint with the FTC. If money moved out of a bank account, contact the bank on the same day, because consumer protection rules give you more leverage when you act fast.
Yes. Possessing and using stolen card data with intent to defraud is a crime even if the first charge fails.
Some sell real stolen data and some sell nothing at all. The legal risk sits with the buyer either way.
Most US credit card issuers limit cardholder liability for unauthorized charges, and the Fair Credit Billing Act gives you a path to dispute them. Debit card rules are narrower and the reporting window matters.
Read your statements, watch your alerts, and review your free credit reports. A tiny test charge of a dollar or two is a common first sign of a stolen card.
Card data theft leaves a real person holding the bill, and the shops that trade it operate outside the law. Buyers face fraud and money laundering charges, sellers face the same, and both sides scam each other. Protecting your own CVV is cheap, quick, and worth doing today.